Allocate shared packaging freight using a stated basis chosen by the buyer's commercial team. Keep the carrier's actual bill separate from the internal allocation, so each SKU's assigned cost can be reproduced without presenting one method as a universal accounting rule.
Identify direct and shared charges
Start with the actual accepted freight invoice or quotation and its shipment reference. Separate charges directly attributable to one SKU from genuinely shared shipment costs. Ask the commercial owner which costs belong in the allocation and how taxes or other accounting items are treated.
The worksheet should reconcile to the accepted total. Do not allocate a charge twice because it appears in both the supplier's delivered quotation and the carrier's separate bill. Mark provisional amounts as estimates and retain the later actual calculation rather than overwriting the original comparison.
Choose a basis and explain why
Possible buyer-selected bases include agreed chargeable contribution, packed volume, gross mass or another documented allocation. They can produce different SKU results. The appropriate choice depends on the actual shipment and the buyer's cost policy, not on a generic claim that heavier or more expensive products must always bear more freight.
DHL explains actual and volumetric chargeable weight. The carrier's charging method can inform the discussion, but it does not prescribe the buyer's internal SKU accounting. Use only a defensible contribution basis with confirmed inputs and the responsible owner's acceptance.
Connect allocation rows to shipment contents
GS1's logistics-label guidance addresses shipping-unit identity. Keep the SKU, carton and quantity links needed to trace the allocation inputs, especially where one carton contains several designs. Do not invent separate carton measurements for mixed contents that were never measured separately.
Decide what the allocation is meant to explain
State whether the worksheet supports a pre-order scenario, an actual shipment cost review or a comparison of SKU profitability under the buyer's policy. An estimate uses quoted or assumed inputs and should remain labelled. An actual allocation uses the accepted charge pool and identified shipment contents. Keep the purpose and calculation date visible so another team does not interpret a planning scenario as a booked accounting result.
Use one shipment reference and one currency basis. If a commercial owner combines several invoices, list them and reconcile the pool. Ask which taxes, credits and additional items belong in the calculation. The article supplies a reproducible worksheet, not an accounting policy. The responsible finance or commercial owner must choose and approve the treatment appropriate to the business.
Separate direct charges before sharing the remainder
Identify a charge that belongs exclusively to one SKU under the accepted records and keep it outside the shared pool where the buyer's policy requires. For example, a specifically documented additional movement for one item may be treated directly. Do not classify a charge by guesswork. Record its source, reason and owner. Then reconcile direct charges plus the shared pool with the accepted shipment total.
Check for duplication with the supplier's delivered price. A carrier invoice can be evidence of freight already included rather than another payable amount. Ask the commercial owner to establish the relationship. The allocation must not distribute the same cost twice simply because two documents exist. Preserve the original documents and the reconciliation so later users can understand how the pool was formed.
Choose inputs that can actually be supported
Possible buyer-selected bases include packed volume, gross mass, an agreed contribution to chargeable space or another stated policy basis. Each needs a clear unit and source. Do not call a row chargeable weight unless the calculation truly represents the agreed service and physical arrangement. Carrier billing can operate at a shipment or piece level that does not naturally separate into independent SKU charges.
Mixed cartons need special care. If two SKUs share one carton, the full external volume cannot be assigned to both. Ask the owner to approve a defensible internal basis and state the assumption. A piece-count allocation may be an accepted choice in one context, but it should not be presented as measured volume. The worksheet is useful when it makes those distinctions visible rather than concealing them behind a formula.
Calculate shares and reconcile them
For each SKU, divide its agreed contribution by the total contribution. Multiply that share by the shared charge pool. Use the same formula for every row. Record enough precision to reproduce the result, then apply the buyer's accepted rounding treatment. Check that allocated amounts sum to the pool. If rounding leaves a residual, assign it using a stated rule approved by the owner rather than changing an input silently.
In the existing illustrative case, contributions of 10 and 20 units sum to 30. A's share is one third and B's two thirds. Applied to Rs 6,000, the allocations are Rs 2,000 and Rs 4,000. Dividing by the stated accepted quantities gives Rs 0.20 per A piece and Rs 0.80 per B piece. The contribution units are assumed teaching inputs, not measurements from an actual shipment or a recommended universal allocation basis.
Show how another accepted basis changes the result
Use an illustrative sensitivity comparison while keeping the Rs 6,000 pool unchanged. If the buyer instead agrees equal contributions, each SKU receives Rs 3,000. With the same assumed 10,000 A pieces and 5,000 B pieces, the results become Rs 0.30 and Rs 0.60 per piece. Both scenarios reconcile mathematically. The different row outcomes arise from the chosen basis, not a change in the carrier's bill.
This comparison is a reason to document policy, not permission to select whichever method makes a preferred SKU look cheaper. Ask the commercial owner which basis supports the decision and why. Preserve the rejected scenario as an illustration if useful, but identify one active method for the actual calculation. Consistency makes later comparisons interpretable, especially when SKU mix changes between shipments.
Define the per-unit denominator separately
State whether the allocation is divided by shipped, received or accepted usable pieces. These quantities can differ and answer different questions. An invoice-based allocation may use one quantity basis while a delivered-usable-unit analysis uses another. Do not switch denominators midway through a comparison. Link the quantity source and status date to each row, keeping holds and later decisions visible.
If a receiving decision changes the accepted quantity, issue a new per-unit view while preserving the original allocation pool and amount unless the commercial treatment also changes. This separates denominator effects from freight effects. A higher per-usable-piece result does not by itself show that the carrier charged more. The cost and quantity movement records explain the difference.
Retain the calculation as an auditable record
Keep charge sources, shipment content links, input basis, approving owner, formula, rounding and quantity status together. Reconcile the actual result against any earlier estimate and explain material changes. At the next shipment, use the current contents and accepted policy rather than copying contribution inputs automatically. The result is a transparent shared-cost allocation that a procurement or B2B reviewer can reproduce, with the carrier's invoice and internal decision remaining clearly distinguishable.
Reconcile rounding and direct charges
Set a rounding rule through the buyer's commercial process and retain sufficient calculation precision before presenting row totals. Check that the assigned amounts reconcile to the accepted shared pool. If a small balancing adjustment is needed, show its method and owner rather than hiding it in an unexplained row.
Keep direct charges outside the pool where the agreed policy assigns them directly. A receiving-site charge or another attributable item should not be spread automatically merely because it appears on the same invoice. When shipment contents or quantity status changes, update the relevant inputs and preserve the previous version. The final worksheet should show the carrier's charge, the buyer's allocation decision and each SKU's accepted denominator as distinct records.
A working record for this decision
Use this original worksheet with your product and supplier team. Give each row a named owner and evidence reference; a blank answer remains an open decision.
| Record | What to enter and why |
|---|---|
| Charge pool | Identify accepted shared freight and directly attributable charges without duplication. |
| Shipment contents | Link SKU, cartons, mixed contents and accepted quantities to the shipment reference. |
| Allocation basis | State the buyer-chosen method, input source, units and approving commercial owner. |
| SKU calculation | Record each contribution, share, allocated amount and per-unit denominator. |
| Reconciliation | Check allocated totals against the charge pool and preserve estimated versus actual versions. |
Freight allocation: a practical specification example
A packaging quote is being compared across two delivery plans. Use the same filled or empty-pack arrangement, quantity and destination in both calculations. A flat-bottom pouch, mailer and reel can occupy very different shipment volumes. Record the actual carton or reel measurements; the unit price of an empty pack does not establish the delivered cost per usable item.
For this decision, start with the mixed SKUs and chosen allocation basis. The useful output is an explicit method instead of an unexplained blended surcharge. Put that output beside the relevant quotation, drawing or sample rather than leaving it in a separate email. This is an illustrative decision exercise, not a report of a completed customer trial.
Product references to make the discussion concrete
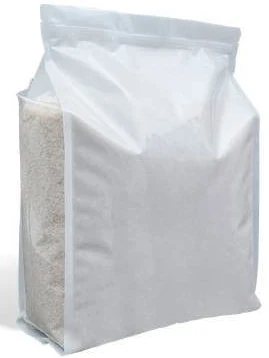
The catalogue includes courier bags and rice packaging bags. These examples show different physical constructions; they are not interchangeable specifications. Courier mailers close with an adhesive flap. Size the usable cavity around the actual item or inner pack, keeping the flap allowance separate. An invoice or POD document pocket can be included in the enquiry; confirm its dimensions and location on the drawing.
| Format reference | Material or construction to clarify | Details to include in the brief |
|---|---|---|
| Courier bags | Flexible mailing-bag film with an adhesive flap; polymer type, opacity and thickness are project specifications. | Item or inner-carton dimensions; usable height excluding the flap. |
| Rice packaging bags | Flexible gusseted bag or pouch construction; film layers, thickness, handle reinforcement and closure are specified for the fill. | Rice type and target net weight; filled envelope and side gusset. |
Use the reference pictures to identify the base, side panels, window or opening that you mean. A picture cannot supply the missing dimensions or material layers. If a photograph shows a finish or closure you do not want, state that difference explicitly; otherwise a visual reference can introduce an unintended requirement.
Complete the record before requesting the next sample
- Attach an explicit method instead of an unexplained blended surcharge. Identify the product or SKU and the date of the observation.
- Record the mixed SKUs and chosen allocation basis. Keep confirmed information separate from proposed values and questions for the supplier.
- Add the actual fill weight or volume, the dimension convention, material proposal and intended closure. Include the number of designs and quantity per design when requesting a quotation.
- State which question the next drawing, sample or quotation must resolve. A change of size, closure or material should remain visible alongside the earlier reference.
This record makes the next conversation specific. It lets the design, purchasing and packing teams work from the same proposed item and shows which decision still needs evidence. Review the related product pages for format details, or prepare a custom packaging brief with the unresolved requirements.
Put the decision into practice
1. Define the shared pool. Separate direct charges and confirm which accepted costs the buyer wants to allocate.
2. Approve the basis. Choose a documented method with the commercial owner and obtain defensible inputs.
3. Calculate and reconcile. Apply the same formula to each SKU and check that assigned amounts equal the shared total.
4. Retain the evidence. Keep shipment references, input sources, quantity status and calculation version for later review.
Request the packed shipment and SKU quantity details from Navkar Poly Print, then apply your commercial team's accepted freight-allocation basis.
Sources and scope.
These references support the technical discussion. Product photographs illustrate formats; the material, dimensions and suitability of the proposed pack are confirmed for each project.
- DHL: calculating chargeable weights
Carrier explains actual versus volumetric weight; buyers must use current route-specific factors and quotations.
- GS1: Logistic Label Guideline
Primary guidance for identifying logistics units; buyer worksheet does not require a GS1 implementation unless agreed.
Let’s discuss your product.
Share your contents, dimensions, filling method, quantity and delivery destination. We’ll work through the proposed packaging specification with you.
Create a packaging brief