Compare packaging on the cost of the usable quantity received, using the same scope and period for every offer. Keep pack price, project charges, delivery and receiving results visible so an apparent unit saving can be checked against the actual purchase.
Define the numerator and denominator
For an initial comparison, list the accepted pack cost and identifiable project, packing and delivery charges. Ask the buyer's commercial team how taxes and internal costs should be treated, and state the basis consistently. Do not remove an uncertain cost or assume it is recoverable without the appropriate review.
Use the accepted usable quantity as a separate denominator once receiving decisions are available. Distinguish invoiced, delivered, accepted, held and rejected quantities. A held pack should not silently become a usable unit just to make the calculation look better.
Keep delivery assumptions visible
DHL explains actual and volumetric chargeable weight. Request the real packed dimensions and route-specific quotation rather than estimating freight from pouch mass alone. Carrier factors and minimums must come from the actual offer.
GS1's logistics-label guidance addresses identifying shipping units. Whatever identification system the parties agree, connect each receipt to its order, SKU and batch information so quantities can be reconciled.
Label estimates and actuals separately
The pre-order calculation uses quoted and assumed values. The post-receipt calculation uses accepted invoices and receiving results. Keep both versions rather than overwriting the estimate, because differences help explain whether freight, quantity or specification changed.
Choose the decision the calculation supports
State whether the model compares supplier offers before purchase, explains one actual receipt or reviews a series of completed orders. Those are different uses of information. A pre-order denominator may be the ordered quantity because acceptance results do not yet exist. Label it estimated and state the assumption. A post-receipt denominator can use the quantity accepted as usable under the buyer's procedure. Do not present the two as directly comparable without explaining the change.
Keep the period and SKU scope consistent. A first-order calculation may include identified project charges that an unchanged repeat does not incur under the accepted offer. A mixed shipment may require a separate buyer-approved allocation across SKUs. State that basis or calculate the shipment as a whole. Dividing all costs by one favoured SKU's quantity would create a precise-looking result with no defensible relationship to the purchase.
Build the numerator from identifiable records
List the accepted pack supply, setup, samples if included in scope, outer packing, freight and other chosen cost categories. Give each line a quotation or invoice reference. Mark whether the amount is confirmed, estimated or unresolved. Ask the commercial owner how to handle taxes, credits and internal costs. An accounting treatment should be stated by the responsible team rather than inferred from the appearance of a supplier invoice.
Avoid duplicate charges. A delivered supplier price may already include the freight later shown on a carrier document. Identify whether that document is evidence of an included cost or an additional payable amount. The same caution applies to preparation bundled into a unit price. Keep the original commercial description visible and document any separation the supplier has actually confirmed. A comparison should not add an assumed component twice merely to make the worksheet look complete.
Reconcile quantity statuses independently
Use a quantity movement table with ordered, invoiced, delivered, accepted, held and rejected states as applicable. Record the date of the status and its source. A physical receipt may be complete while technical review remains open. If held stock later becomes accepted, update the calculation through a new version. Preserve the earlier result so the team can understand why the denominator changed without assuming the original record was an arithmetic mistake.
For the illustrative 20,000-piece receipt, 19,600 pieces are accepted and 400 remain held. The accepted fraction is 19,600 divided by 20,000, or 98%, on those invented figures. This is a status reconciliation, not a supplier quality result. The cause and eventual disposition of the hold remain separate questions. Do not label the held quantity defective, count it as usable or presume it will be rejected to improve the story told by the model.
Show the effect of an unresolved quantity
The existing illustrative numerator is Rs 55,000. With 19,600 accepted pieces, the result is about Rs 2.806 per accepted piece. If the remaining 400 are later accepted and no other costs change, Rs 55,000 divided by 20,000 equals Rs 2.75. State both conditions explicitly. The difference comes from the denominator; it is not evidence that freight became cheaper or that the supplier improved its pack price.
If additional rework, return transport or a credit is later agreed, record it as a separate change to the chosen cost scope. The buyer's commercial owner should decide how it belongs in the model. Do not insert hypothetical recoveries as though they are accepted facts. A scenario can be useful, but label it illustrative and keep it outside the actual result until the relevant record exists.
Explain variances by cause
Compare estimate and actual using a short bridge: pack quantity or price, project scope, packing, transport, other accepted costs and quantity status. Change one line at a time when explaining the difference. This helps readers distinguish a more expensive shipment from a smaller usable denominator. A single percentage variance can conceal several unrelated changes and encourage the wrong corrective action.
Ask which variances were foreseeable from the original quote and which arose later. An unresolved freight line should have remained unknown in the estimate. A changed destination is a scope revision. A receiving hold requires its own technical record. The purpose of the bridge is to improve the next decision, not assign blame from a financial total that contains no evidence of cause.
Keep comparison options honest
When evaluating another offer, use the same numerator categories and quantity assumptions. Do not give one supplier an actual accepted quantity while giving the other a perfect hypothetical receipt. If meaningful acceptance data are unavailable, state the common assumption and leave performance differences unclaimed. The buyer can compare known commercial scope without inventing reject rates, returns or operational savings.
Present the result with its currency, unit, rounding and calculation date. Retain enough precision internally to reproduce the division, while displaying a practical rounded value. Attach the source records and unresolved decisions. The useful outcome is a transparent cost per usable unit for a defined purchase, with the reasons for change visible and the technical acceptance process preserved independently of the arithmetic.
Track cost and receipt adjustments
Keep subsequent commercial adjustments traceable to their actual source. A credit, replacement shipment or added handling charge can change the comparison, but the buyer's commercial team must decide its treatment and timing. Preserve the original receipt and cost version before showing the revised result.
If held material is eventually accepted, update its status through the authorised receiving decision. If another action is agreed, retain that decision and associated cost records instead of editing the earlier event out of history. The model should explain which input changed: quantity eligibility, a charge or another stated assumption. That distinction makes the final amount reproducible without suggesting an unsupported cause or complete accounting treatment.
For a multi-SKU receipt, retain the row-level quantities even if the first calculation is shipment-wide. If a later reviewer needs a SKU view, use a documented allocation basis and the same accepted cost pool. This avoids recreating a convenient split after seeing the result and keeps both views connected to the original purchase.
A working record for this decision
Use this original worksheet with your product and supplier team. Give each row a named owner and evidence reference; a blank answer remains an open decision.
| Record | What to enter and why |
|---|---|
| Cost scope | List included cost categories and the commercial treatment agreed by the buyer team. |
| Quoted receipt | Record SKU quantities, packed dimensions, weight and delivery quotation references. |
| Quantity statuses | Separate invoiced, delivered, accepted, held and rejected units with receiving evidence. |
| Calculation basis | State numerator, denominator, currency and rounding in the comparison. |
| Variance record | Compare estimate and actual result with reasons for freight, scope or quantity changes. |
Delivered packaging cost: a practical specification example
A packaging quote is being compared across two delivery plans. Use the same filled or empty-pack arrangement, quantity and destination in both calculations. A flat-bottom pouch, mailer and reel can occupy very different shipment volumes. Record the actual carton or reel measurements; the unit price of an empty pack does not establish the delivered cost per usable item.
For this decision, start with the included charges and usable quantity. The useful output is a cost table using the same denominator. Put that output beside the relevant quotation, drawing or sample rather than leaving it in a separate email. This is an illustrative decision exercise, not a report of a completed customer trial.
Product references to make the discussion concrete
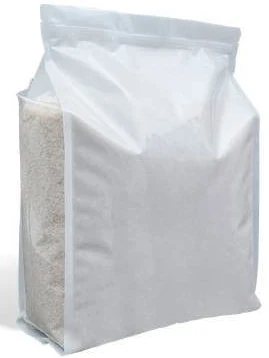
The catalogue includes courier bags and rice packaging bags. These examples show different physical constructions; they are not interchangeable specifications. Courier mailers close with an adhesive flap. Size the usable cavity around the actual item or inner pack, keeping the flap allowance separate. An invoice or POD document pocket can be included in the enquiry; confirm its dimensions and location on the drawing.
| Format reference | Material or construction to clarify | Details to include in the brief |
|---|---|---|
| Courier bags | Flexible mailing-bag film with an adhesive flap; polymer type, opacity and thickness are project specifications. | Item or inner-carton dimensions; usable height excluding the flap. |
| Rice packaging bags | Flexible gusseted bag or pouch construction; film layers, thickness, handle reinforcement and closure are specified for the fill. | Rice type and target net weight; filled envelope and side gusset. |
Use the reference pictures to identify the base, side panels, window or opening that you mean. A picture cannot supply the missing dimensions or material layers. If a photograph shows a finish or closure you do not want, state that difference explicitly; otherwise a visual reference can introduce an unintended requirement.
Complete the record before requesting the next sample
- Attach a cost table using the same denominator. Identify the product or SKU and the date of the observation.
- Record the included charges and usable quantity. Keep confirmed information separate from proposed values and questions for the supplier.
- Add the actual fill weight or volume, the dimension convention, material proposal and intended closure. Include the number of designs and quantity per design when requesting a quotation.
- State which question the next drawing, sample or quotation must resolve. A change of size, closure or material should remain visible alongside the earlier reference.
This record makes the next conversation specific. It lets the design, purchasing and packing teams work from the same proposed item and shows which decision still needs evidence. Review the related product pages for format details, or prepare a custom packaging brief with the unresolved requirements.
Put the decision into practice
1. Set a common basis. Agree cost categories and quantity units before comparing supplier offers.
2. Collect the full quote. Obtain identified project and delivery charges instead of treating missing amounts as zero.
3. Reconcile receipt. Use the accepted receiving record to establish usable quantity and unresolved holds.
4. Explain the difference. Retain estimated and actual results with a short variance explanation for the next purchase.
Ask Navkar Poly Print for the pack, project and packed-shipment details needed to compare your actual delivery quotation on a consistent basis.
Sources and scope.
These references support the technical discussion. Product photographs illustrate formats; the material, dimensions and suitability of the proposed pack are confirmed for each project.
- DHL: calculating chargeable weights
Carrier explains actual versus volumetric weight; buyers must use current route-specific factors and quotations.
- GS1: Logistic Label Guideline
Primary guidance for identifying logistics units; buyer worksheet does not require a GS1 implementation unless agreed.
Let’s discuss your product.
Share your contents, dimensions, filling method, quantity and delivery destination. We’ll work through the proposed packaging specification with you.
Create a packaging brief